Abstract
Economic systems are frequently defended by reference to their declared ownership arrangements: productive property belongs to the people, individuals are free to establish enterprises, or investors enable founders to build companies of their own. These descriptions leave unresolved the decisive question of effective agency: what can an ordinary productive participant actually acquire, direct, retain, transfer, and defend? This article develops a longitudinal ownership audit that evaluates institutions through the trajectories of the people whose contributions sustain them. It distinguishes legal entitlement, effective control, realized compensation, and durable personal independence; examines the separation of collective ownership from worker control in the Soviet command economy; and analyzes how entrepreneurial financing can convert a founder’s labor and know-how into transferable assets without delivering meaningful ownership to the founder. Particular attention is given to unequal starting positions and to the use of selected founder success stories as evidence of general opportunity. The article’s contribution is a conceptual framework and an empirical research design, not an estimate of the prevalence of extraction. Its central thesis is that neither investment in an enterprise nor the enrichment of selected participants establishes that a financing system enables productive people without prior wealth to become independent owners. That claim must be evaluated by tracing contributions, contractual changes, surviving assets, and realized outcomes across complete participant cohorts.
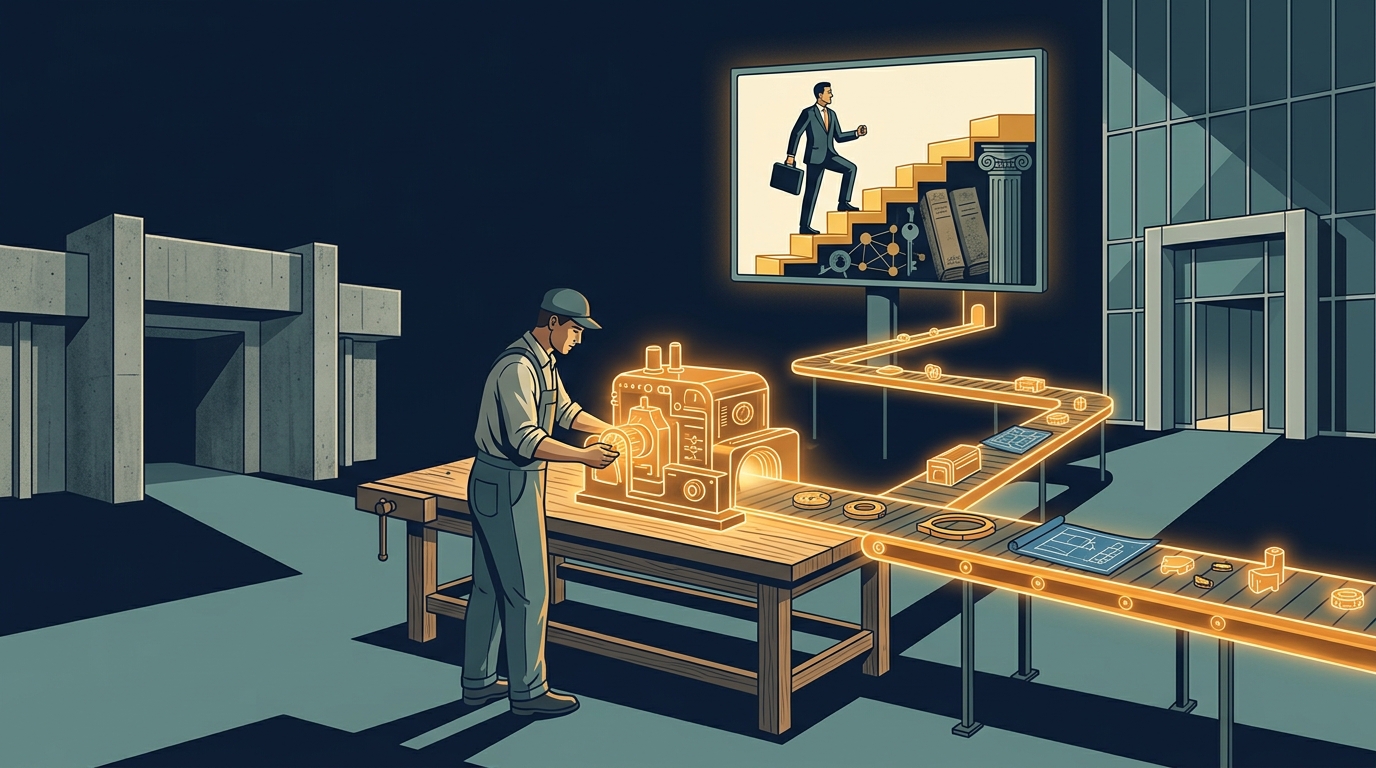
Central thesis: A system that mobilizes productive effort through the promise of ownership must be judged by whether that effort produces effective ownership for the contributor—not merely by whether it produces a valuable asset for someone else.
1. Introduction: The Institutional Promise Is the Object of Inquiry
The conventional opposition between capitalism and socialism organizes debate around the identity of the legal owner. Private property, state property, and collective property become proxies for freedom, exploitation, efficiency, or justice. The proxies then replace the relationships they were supposed to describe.
This article reverses that order of analysis. It begins with a person and follows what institutions allow that person to do. The relevant participant is not the exceptional individual selected for publicity, but the person who brings productive ability without already possessing substantial wealth, political access, or control over resource allocation.
The question is not simply whether this person is permitted to participate. It is whether participation creates a practicable route to independent agency, or whether institutional arrangements separate the person’s contribution from the rights and returns that contribution was expected to secure.
This is an immanent critique: it evaluates institutions against the claims through which they justify themselves. Where a state invokes popular ownership, the investigation concerns the people’s effective authority over its assets and administrators. Where entrepreneurial finance invokes founder ownership, the investigation concerns the founder’s actual trajectory from contribution to control and realized return.
The promise of universal entrepreneurial opportunity is not the whole definition of capitalism. Nor is Soviet state ownership the whole definition of socialism. They are influential justificatory claims attached to particular institutional arrangements. Their importance lies in the work they perform: legitimating control and encouraging participation.
The assertion that an institution serves the contributor cannot also serve as evidence that it does so.
The analysis therefore separates three questions commonly collapsed into one:
- Does the arrangement mobilize resources and produce something valuable?
- Who obtains decision-making authority and economic benefit from that production?
- Does the outcome substantiate the ownership or empowerment claim made to participants?
An institution can succeed at the first while failing the second and third from the contributor’s perspective. Indeed, obtaining productive effort without granting durable claims to its suppliers can be advantageous to those controlling the institution. What appears as a failure of the public promise may constitute a success of the operative mechanism.
2. Theoretical Foundations: Property, Capabilities, and Effective Control
2.1 Ownership is not exhausted by a title
Property rights theory provides a starting point for distinguishing formal ownership from particular decision rights. Grossman and Hart’s analysis of incomplete contracts identifies ownership with residual rights of control: authority over uses of assets not fully specified by contract (1986). Its importance here is analytical. When unforeseen circumstances arise, someone must possess the authority to decide what happens, and allocating that authority affects incentives and bargaining positions.
This does not imply that every shareholder controls a company’s assets. The company, shareholder, board, management, and secured creditor occupy different legal positions. A shareholding is a claim within that structure, not a personal right to operate every asset or withdraw a proportional amount of company cash.
Consequently, an ownership audit must identify the asset and the level of analysis. Does a person own a patent, shares in a company that owns the patent, or an unvested contractual expectation of receiving those shares? Who can license the patent, approve its sale, replace management, and determine distributions?
These distinctions are not technical distractions. They specify where effective authority resides.
2.2 Formal freedom and substantive opportunity
The capability approach distinguishes possession of resources or formal rights from the substantive opportunities those resources and rights make possible. Sen’s framework, reviewed by Robeyns and Byskov (2025), asks what people are actually able to do and be, taking account of the conditions through which resources become usable freedoms.
Applied to ownership, the distinction is immediate. Two people can have the same legal permission to establish a business while possessing radically different capacities to survive its development, negotiate financing, challenge misconduct, or refuse an offer.
A right that requires years of litigation and resources the holder does not possess may have little protective force at the moment it is needed. A permission to reject financing does not establish a practicable alternative when rejection means losing housing or abandoning an otherwise viable project.
Effective agency therefore includes both the authority to decide and the material ability to exercise that authority. It is relational and institutional, not simply an attribute of individual confidence, intelligence, or determination.
2.3 The five dimensions of the ownership audit
The proposed framework examines five distinct dimensions:
| Dimension | Operational question | Relevant evidence |
|---|---|---|
| Acquisition | Can a participant realistically obtain productive resources? | Entry costs, financing access, collateral requirements, personal runway, available alternatives |
| Direction | Which consequential decisions can the participant make or contest? | Voting rights, board appointment rights, vetoes, management authority, enforceable participation rights |
| Value capture | What does the participant actually receive from production? | Compensation, distributions, priority claims, realized sale proceeds, liabilities |
| Transfer | Can the participant dispose of, retain, or refuse to transfer their interest? | Transfer restrictions, sale provisions, licensing rights, practical liquidity |
| Protection | What prevents unilateral deprivation or override? | Due process, independent review, enforcement costs, remedies, protection against retaliation |
These dimensions should initially be reported separately. A single ownership score would require contestable assumptions about whether, for example, income compensates for the absence of voice or whether a formal veto compensates for an inability to survive its exercise.
The audit also distinguishes ownership from unlimited authority. Environmental obligations, workers’ rights, taxation, and accountable regulation can constrain ownership without nullifying it. The relevant question is whether constraints preserve reciprocal rights and contestability, rather than whether the owner is exempt from obligations to others.
3. From Entry Conditions to Ownership Trajectories
An entry-based evaluation asks whether people may register enterprises, apply for investment, or receive shares. A trajectory-based evaluation asks what happens after they do so.
The relevant sequence extends from access to resources through production, financing, organizational change, realization of value, and subsequent independence. Rights may expand at one stage and contract at another. A nominal owner can become a dependent manager; a founder can sell voluntarily and acquire substantial independence; a worker can acquire meaningful collective rights without becoming a sole proprietor.
Three objects must therefore be tracked together:
- The person: compensation, liabilities, authority, livelihood, and alternatives.
- The contribution: labor, savings, technical knowledge, relationships, and other inputs.
- The resulting asset: its ownership, uses, transfers, income, and continued existence.
Tracking only the company loses the founder after departure. Tracking only the founder loses the asset after a transfer. Tracking only investment records leaves uncompensated labor and foregone income outside the apparent resource flow.
This also clarifies what it means to keep something. Retaining a controlling stake, receiving a substantial voluntary buyout, and preserving a secure income with collective decision rights are different outcomes. They should not be conflated, but each can represent a real gain for the participant. Paper value without usable rights or realizable benefit cannot simply be substituted for any of them.
The normative requirement is not a guaranteed entrepreneurial fortune. It is that a system invoking productive opportunity be assessed by a defensible account of how participation changes people’s lives. An occasional winner establishes possibility. It does not establish accessibility, reliability, or the distribution of risk.
4. State Ownership and the Substitution of the Representative
The Soviet case makes the gap between declared ownership and effective control especially clear. Articles 5 and 6 of the 1936 Constitution identified state property as belonging to the whole people. Article 11 placed economic life under the national economic plan. The same constitutional framework assigned the Communist Party a leading position within public and state organizations in Article 126 (USSR, 1936, amended text).
The constitution also described elections, reporting obligations, and recall. An audit cannot infer effective popular control from those provisions any more than it can infer individual control from a share certificate. The institutional question is whether citizens could independently organize to challenge and replace the authorities directing productive assets, and whether those mechanisms worked against entrenched administrative interests.
Kornai’s account of the classical socialist system situates state ownership within a broader structure of party dominance and bureaucratic coordination (1992). In the mature Soviet command economy, an ordinary worker’s employment in a state enterprise did not give that worker an independently enforceable authority to dispose of its assets or remove the party-state hierarchy overseeing production.
Collective ownership need not mean that every member may sell a factory or veto every decision. It requires an effective chain of collective authorization and accountability. The defect is not the absence of unilateral individual command; it is the absence of workable control by the collective said to be the owner.
The constitutional text itself distinguishes state property, cooperative property, and limited forms of private production. These arrangements must be examined separately. The general failure mechanism under discussion is representative substitution: an institution claims to exercise ownership for a constituency while retaining decisive authority that the constituency cannot effectively contest.
Employment, education, or social provision do not settle that issue. Benefits supplied to a population and authority exercised by that population are different dimensions of institutional performance. A beneficiary is not thereby an owner.
5. Entrepreneurial Finance: What, Exactly, Is Being Financed?
5.1 The company is not the founder
In entrepreneurial finance, the corresponding question is whether financing enables a productive person to become an independent owner—or acquires that person’s contribution on terms that leave ownership elsewhere.
An investment announcement establishes that resources entered an enterprise under specified terms. It does not establish that the founder has been adequately compensated, retains meaningful control, or will obtain any realizable benefit from the resulting asset.
The founder supplies resources too. These may include cash, uncompensated development, below-market labor, intellectual property, customer relationships, and years of foregone earnings. Future equity is often the expected consideration for accepting an immediate shortfall in compensation. That expectation gives the final allocation of value a central role in evaluating the exchange.
If the investor’s cash is counted as financing but the builder’s unpaid contribution is treated as free background, the accounting has already assigned legitimacy asymmetrically.
A complete account records both. It does not presume that every hour creates market value or that effort establishes sole ownership. It asks which contributions were necessary, which compensation was received, and which claims survived.
5.2 Rights are allocated separately
Kaplan and Strömberg’s study of venture capital contracts documents the separate allocation of cash-flow rights, voting rights, board rights, liquidation rights, and other control rights (2003). Their evidence also shows that allocations can depend on performance: poor performance can increase investor control, while strong performance can leave entrepreneurs with more control and investors with fewer intervention rights.
The result establishes why neither dilution nor a funding round is an adequate summary of the founder’s position. Contractual changes have to be reconstructed across distinct rights and performance states. A smaller economic percentage does not necessarily mean less voting control; substantial nominal equity does not necessarily entail substantial liquidation proceeds.
Hellmann and Puri find that venture-backed firms in their Silicon Valley sample were more likely, and quicker, to replace a founder with an outside chief executive. Their evidence includes both apparently adversarial and mutually agreed replacements (2002). Replacement is thus a concrete governance event to investigate, not an automatic measure of dispossession. The ownership audit asks what happened to the departing founder’s compensation, vested rights, and eventual proceeds.
These studies establish relevant contractual and organizational mechanisms. The extraction thesis concerns how those mechanisms interact with initial inequality and the distribution of surviving value.
5.3 The conversion of know-how into a separable asset
The founder trap operates through a sequence:
- A contributor enters with knowledge or productive ability but insufficient resources to develop it independently.
- Expected future ownership supports a period of unpaid or underpaid work.
- That work becomes embodied in company-controlled code, patents, processes, relationships, and organizational routines.
- Further resources become conditional on rights that place decisive authority elsewhere.
- The contribution becomes usable without the contributor, whose employment and economic claims can then be reduced or terminated under the relevant arrangements.
Not all knowledge becomes fully transferable. The mechanism concerns the portion that does: code others can maintain, patents others can license, processes others can reproduce, or relationships the organization can retain.
The critical transition is from the institution needs this person to create the asset to the institution controls an asset it can use without this person. If the person’s claim remains fragile during that transition, successful productive work can reduce their indispensability without securing their independence.
The founder has then helped finance the creation of someone else’s controllable asset through a sacrifice justified by expected ownership.
5.4 A worked example: value survives, common equity does not pay
Consider a hypothetical enterprise sold for 8 million monetary units. Assume it owes 1 million in debt and has one class of preferred shares with a 7 million non-participating liquidation preference. Assume the preferred holders’ alternative payout on conversion is lower, and ignore taxes and transaction costs.
The debt receives 1 million. Preferred holders elect their 7 million preference. Nothing remains for common shareholders, including a founder who supplied years of below-market work.
The business has a buyer, a sale price, and assets that continue to be used. The founder’s common equity nevertheless produces no payout. A headline announcing an acquisition cannot reveal this distribution.
The example does not establish that investors made a profit: the preference could merely return their invested principal. It establishes that continuing asset value, company-level liquidity, investor recovery, and founder compensation are separate quantities. Determining whether the transaction constitutes extraction requires examining the preceding bargain, the founder’s compensation, available alternatives, and the control exercised over the sale.
The stronger evidence would include strategically imposed refinancing, conflicted asset transfers, misleading representations about rights, or the use of financial distress to extinguish contributors’ claims while retaining their work. The category should be defined through those relationships, not inferred from the word acquisition or failure.
6. Unequal Starting Positions Produce Different Founder Paths
6.1 Productive ability and bargaining leverage are different resources
The category founder combines people whose institutional positions are fundamentally different. A wealthy founder can absorb delay, purchase independent advice, finance early development, and reject unfavorable terms. A founder without reserves must negotiate against personal and organizational deadlines.
This makes time an allocative instrument. Where one side can wait and the other cannot, postponement changes the bargaining environment without improving the product or supplying additional resources. Successive demands for milestones can require the builder to contribute more before financing becomes secure.
The relevant distinction is not between hardworking and idle individuals. It is between the capacity to produce value and the capacity to withhold cooperation until acceptable terms are available. Additional effort can increase the former while depletion of savings reduces the latter.
A founder can therefore produce an exceptional product and still confront inferior terms. Ownership outcomes cannot be read backward as a ranking of productive merit.
6.2 Wealth, recognized status, and institutional sponsorship
Starting advantage includes more than current bank balances. Family resources, credible access to future wealth, trusted introductions, prior organizational standing, and influential sponsorship can affect how a founder’s prospects are assessed and which terms are offered.
These channels must be distinguished empirically. Personal wealth provides runway. A network provides access. Sponsorship can confer credibility or favorable treatment without making the founder independently wealthy. Combining them into an undifferentiated category of talent conceals how opportunity is allocated.
Research on wealth and entrepreneurship also demonstrates the importance of specifying the outcome. Hurst and Lusardi (2004) challenge a simple interpretation of the wealth–business-entry relationship as general evidence of binding liquidity constraints; their analysis identifies a nonlinear relationship concentrated at the upper end of the wealth distribution. Business entry is not the same outcome as retained control after repeated financing. The ownership audit requires evidence on each stage rather than treating an entry study as a complete verdict on the trajectory.
The research question is correspondingly sharper: among contributors developing comparable enterprises, how do initial resources and institutional access affect financing terms, the capacity to refuse, and the ultimate division of control and returns?
6.3 Three trajectories concealed by one public label
Three analytically distinct paths can all be advertised as founder success:
| Trajectory | Starting position | What the outcome demonstrates |
|---|---|---|
| Extension of existing control | Substantial wealth or leverage before founding | The ability to deploy prior advantage through an enterprise |
| Acquisition of independent ownership | Productive ability without substantial prior leverage | A realized transition from contribution to durable agency |
| Prominence without independence | Visibility or sponsorship while decisive rights remain elsewhere | Public recognition, which must be evaluated separately from ownership |
The first trajectory cannot establish the accessibility of the second. The third cannot establish that the person publicly associated with a company directs it or receives its gains.
This distinction identifies the central evidentiary error in the entrepreneurial success narrative: outcomes produced through existing control are presented as evidence that the system distributes control according to contribution.
7. Success Narratives as a Selection Mechanism
7.1 The advertised sample is not the participant population
Public success stories are selected through several filters: entry into entrepreneurship, access to financing, company survival, founder retention, financial outcome, and publicity. A person who disappears at any stage can disappear from the evidence used to defend the institution.
Selection can also operate on usefulness to the storyteller. Investors, companies, governments, and media organizations have reasons to foreground examples that validate their activities. A founder whose image promotes an institution may be highly visible whether or not that founder holds independent authority within it.
The appropriate response is not speculation about an individual’s motives. It is an audit of the selection process. Who chooses the examples? Which starting resources are disclosed? Are wealth and control verified? Where are the contributors whose assets survived but whose participation did not?
A success story is not an answer to a structural criticism. It is an observation whose selection and trajectory require explanation.
7.2 When the asset survives but the contributor disappears
Suppose a founder is removed, a company is wound down, and its technology is sold to a successor enterprise. A company database may classify the original venture as failed. A later account may celebrate the successor’s product without retaining the original contributor in its narrative.
A study that stops at corporate dissolution records loss without examining transfer. A study that begins with the successor records innovation without examining its provenance. The ownership audit links the two.
This is not a demand to attribute every later improvement to an original founder. Subsequent contributors must also be counted. It is a demand that institutional restructuring not erase the record of who supplied valuable inputs and what they received.
The same principle applies to public enterprises: aggregate output and exemplary-worker publicity cannot establish the actual distribution of authority among workers, administrators, and political officials.
8. The Comparison: Common Diagnostic, Different Institutions
The Soviet worker and the venture-backed founder are not interchangeable historical subjects. Political rights, legal remedies, contractual relations, competition, and exit opportunities differ. These differences alter both the mechanisms of control and the practical consequences of losing it.
The comparison concerns a shared institutional problem: the person invoked as the beneficiary or owner can be separated from the authority and benefit used to justify their participation.
In representative substitution, administrators claim to act for the collective while the collective lacks effective means to direct them. In the founder trap, the expectation of future ownership secures productive contribution while control over the resulting asset and its proceeds moves elsewhere.
The temporal structures differ. Collective ownership can be nominal from the outset. Founder ownership can initially be substantive and then become progressively subordinate or economically empty. An audit restricted to the starting point would miss the latter precisely because the initial ownership was real.
Applying the same standard does not presume identical outcomes. It prevents institutional labels from deciding the result before the relevant relationships have been examined.
9. An Empirical Research Design
9.1 Define the claim, population, and observation period
The empirical unit should be the participant–enterprise relationship observed over time, linked to subsequent asset transfers. Studies should specify jurisdiction, industry, financing model, founding cohort, and the period over which outcomes are measured.
Claims about venture-backed firms require a venture-finance sample. Claims about entrepreneurial opportunity require a broader sample, including self-funded firms, rejected applicants, and people unable to enter. These answer different questions and should be reported separately.
Follow-up must include departed founders, dissolved entities, asset sales, and successor organizations. An ongoing firm should not be classified as a completed success merely because the observation period ends before its founder receives anything.
9.2 Record contributions, rights, and realized outcomes
An ownership audit needs linked records in six areas:
- Initial conditions: liquid wealth, debt, housing security, dependants, prior income, experience, networks, and access to independent advice.
- Contributions: invested cash, compensation received, labor supplied, assigned intellectual property, and identifiable organizational contributions.
- Financing history: applications, offers, rejections, delays, funding milestones, contractual revisions, and alternative sources available at each stage.
- Governance: voting rights, board composition, vetoes, employment changes, vesting, transfer restrictions, and dispute mechanisms.
- Realization: salary, distributions, secondary sales, exit proceeds, priority payments, taxes, liabilities, and the destination of surviving assets.
- Subsequent agency: financial security, ability to refuse further dependent arrangements, continuing participation rights, and freedom to undertake another project.
Foregone income should be estimated against stated alternatives, not treated as an unquestionable market wage. Private-company equity should not be valued by multiplying a common shareholding by the price of a preferred share with different rights. Product quality should be measured independently of fundraising prestige wherever possible.
9.3 Distinguish risk sharing from extraction
Four outcome categories help prevent conceptual substitution:
- Developmental financing: resources expand production while contributors obtain the compensation, rights, and realizable benefits needed to substantiate the ownership claim.
- Genuine commercial loss: resources are consumed without sufficient recoverable value, with losses evaluated against the agreed and practically available risk-sharing arrangement.
- Compensated transfer: a contributor relinquishes control in exchange for a meaningful realized return through a substantively available choice.
- Extractive transfer: valuable contributions persist under others’ control while the contributor’s expected ownership return is defeated through arrangements exploiting dependence, unilateral leverage, or an absence of effective accountability.
These are evaluative categories, not automatic labels generated by an exit code. A study should publish the criteria used, document ambiguous cases, and test how findings change under alternative compensation and fairness benchmarks.
9.4 Identify mechanisms rather than merely correlations
An association between external finance and founder removal does not identify the causal effect of financing. Firms seeking investment differ from firms that do not, and investors select among applicants. Likewise, initial wealth is associated with education, networks, industry choice, and the ability to attempt multiple ventures.
Matched comparisons, longitudinal models, and credible policy or institutional changes can help distinguish these channels. Each requires explicit assumptions. Contract histories and interviews can establish sequences that aggregate outcome data miss, but interviews should be checked against contemporaneous records where available.
Evidence supporting the founder-trap account would include a recurring link between weak outside options, uncompensated contributions, loss of substantive claims, and continued use of the resulting assets by others. Evidence against that account would include broadly accessible financing that delivers durable rights or meaningful realized returns to low-wealth contributors, including those who depart, without systematic dependence on prior leverage.
This makes the claim falsifiable without presuming that the system works. The burden is to show what financing does to the contributor, not merely what it does to the company.
9.5 Report distributions, not trophies
Report outcomes across initial-wealth and access groups, including the lower tail, not only average returns inflated by rare exits. Separate gross proceeds from net proceeds, company value from personal wealth, and publicity from authority.
Document missing outcomes, particularly where confidentiality, informal settlements, or incomplete records obscure departures. Missing people must not silently become successful participants or irrelevant failures.
10. Beyond Founder Sovereignty: Symmetry and Institutional Design
The critique of founder dispossession does not establish a founder’s exclusive entitlement to everything an enterprise produces. Employees, co-founders, public research institutions, communities, and investors can all contribute necessary resources. The audit must follow them too.
Protecting a founder’s control while leaving workers without voice, adequate compensation, or security would relocate the problem rather than resolve it. Neither entrepreneurial origin nor technical brilliance authorizes unaccountable control over other contributors.
Institutional proposals should therefore be evaluated by their effects on the five ownership dimensions. Relevant interventions include:
- Reducing survival dependence: portable benefits, social insurance, and development funding that allow contributors to negotiate without immediate destitution.
- Making claims intelligible: independent advice and clear disclosure of voting rights, vesting, liquidation priorities, and plausible payout scenarios.
- Protecting contribution through transitions: enforceable compensation, scrutiny of forfeiture terms, and review of conflicted recapitalizations or asset sales.
- Expanding accountable participation: worker representation, credible grievance mechanisms, information rights, and governance arrangements that participants can actually use.
- Diversifying financing routes: cooperative finance, public funding, customer finance, debt, and equity structures assessed by their distinct risks and allocations of authority.
- Making outcomes auditable: privacy-protecting reporting of participant compensation and control, including departures and transfers that disappear from success narratives.
Each intervention has costs and trade-offs. Debt can preserve equity while imposing repayment risk. Grants can reduce dependence on investors while creating dependence on administrators. Cooperative ownership can distribute formal votes while leaving informal hierarchies intact. These are reasons to apply the audit to the alternative, not to exempt the incumbent arrangement from scrutiny.
Intergenerational transfer requires the same symmetry. An asset that gives one family durable security can become a barrier for the next person without inherited wealth. The criterion cannot be permanent control for today’s successful founder alone. It must include continued access for tomorrow’s productive participant.
Finally, human standing does not depend on entrepreneurial output. Care work, disability, childhood, retirement, and other forms of dependence cannot be excluded from economic evaluation. This article examines ownership claims attached to productive participation; it does not make productive performance a condition of dignity or basic security.
11. Conclusion: Judge the Distribution of Effective Agency
The dispute over economic systems becomes more rigorous when institutional descriptions cease to function as verdicts. Public ownership does not establish public control. Permission to found a company does not establish an accessible route to durable ownership. Investment does not establish that the person supplying productive knowledge has been financed into independence.
The decisive inquiry follows the entire relationship: who enters with leverage, who contributes resources, how knowledge becomes an asset, how rights change, what value survives, and who can finally keep, direct, or refuse its use.
This framework also exposes the inadequacy of selected founder success stories. A wealthy participant extending prior control does not demonstrate that productive effort confers control on someone starting without it. An institutionally celebrated founder does not demonstrate independent ownership. A successful product does not demonstrate a successful outcome for the person who created it.
The central criticism is therefore not that an otherwise vindicated system occasionally distributes rewards imperfectly. It is that the system’s claim to enable ownership remains unproven when its evidence records investment and visible winners while omitting the contributors whose work survives without their claims.
Where a mechanism repeatedly converts productive contribution into assets controlled by others while leaving contributors without meaningful return, the failure is not peripheral to the ownership promise. It concerns what the mechanism actually does.
Forget the isms as verdicts. Examine them as institutional arrangements. Follow the person, follow the contribution, and follow the surviving asset. Then judge the system by the distribution of effective agency it produces.
References
Grossman, S. J., & Hart, O. D. (1986). The costs and benefits of ownership: A theory of vertical and lateral integration. Journal of Political Economy, 94(4), 691–719. https://doi.org/10.1086/261404.
Hellmann, T., & Puri, M. (2002). Venture capital and the professionalization of start-up firms: Empirical evidence. The Journal of Finance, 57(1), 169–197. https://doi.org/10.1111/1540-6261.00419.
Hurst, E., & Lusardi, A. (2004). Liquidity constraints, household wealth, and entrepreneurship. Journal of Political Economy, 112(2), 319–347. https://doi.org/10.1086/381478.
Kaplan, S. N., & Strömberg, P. (2003). Financial contracting theory meets the real world: An empirical analysis of venture capital contracts. The Review of Economic Studies, 70(2), 281–315. Working-paper version and publication record.
Kornai, J. (1992). The socialist system: The political economy of communism. Princeton University Press.
Robeyns, I., & Byskov, M. F. (2025). The capability approach. The Stanford Encyclopedia of Philosophy. Substantive revision April 17, 2025. https://plato.stanford.edu/entries/capability-approach/.
Union of Soviet Socialist Republics. (1936). Constitution (Fundamental Law) of the Union of Soviet Socialist Republics. Amended text reproduced in Works, Vol. 14, Red Star Press, 1978; online transcription by Marxists Internet Archive. Articles 5–11, 126, and 134–142. Constitution text.